March 1, 2026
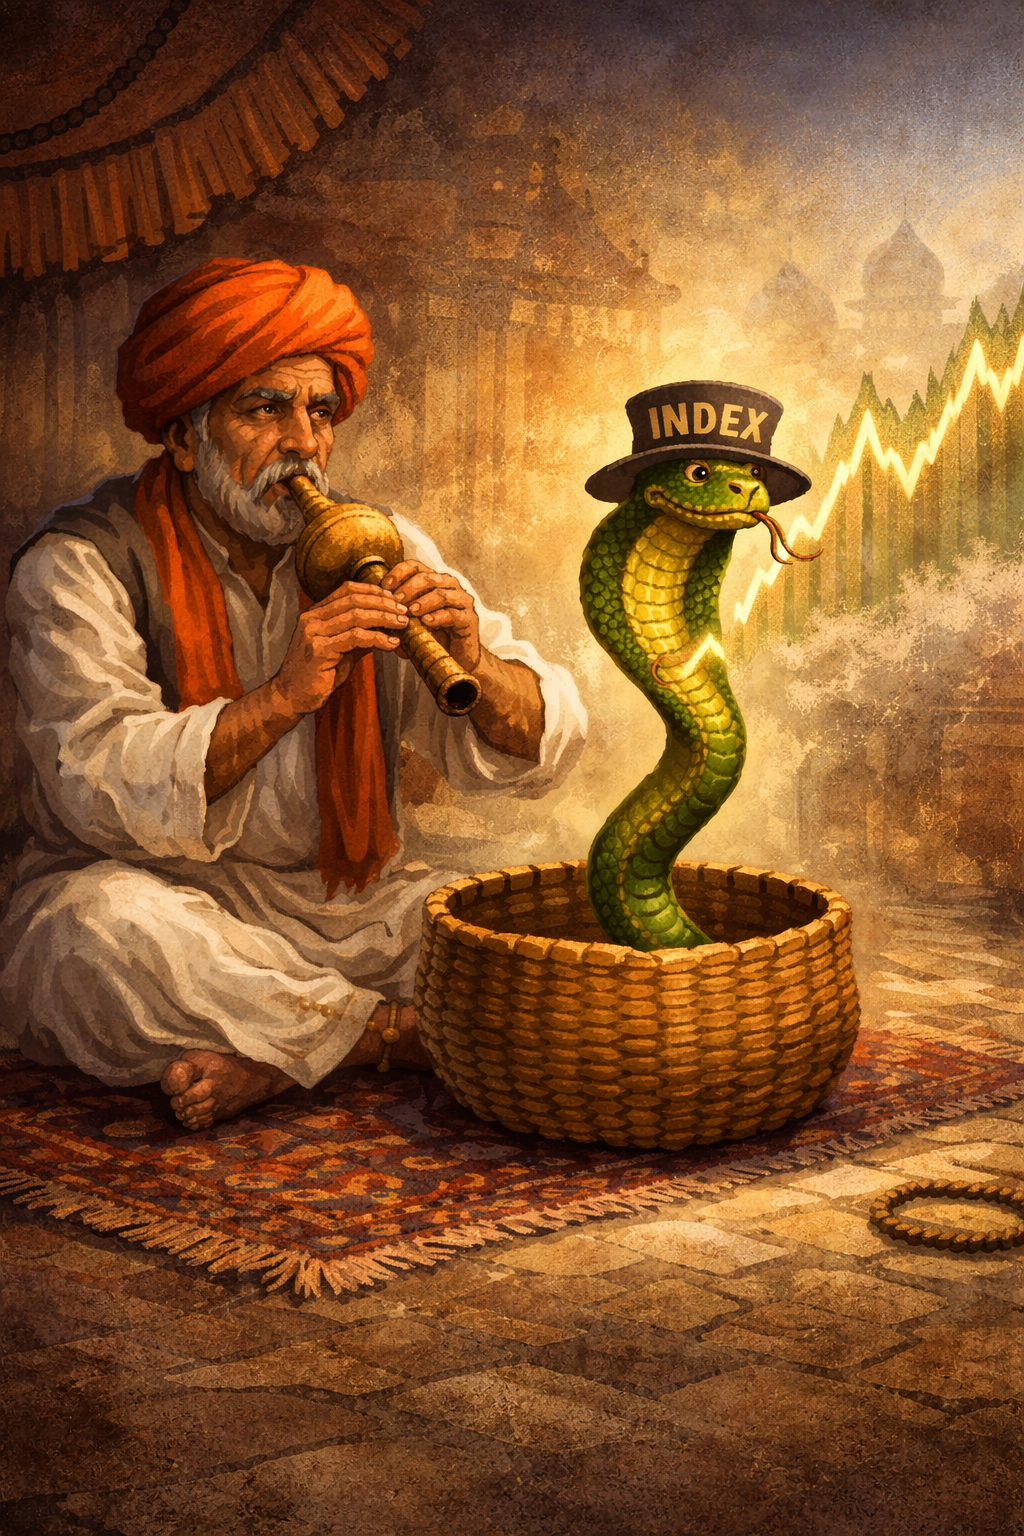
Wall Street – The Great Snake Charmer
The practice of snake charming has a long history in places like India and Egypt, where snakes were associated with deities. The snake charmer plays his clarinet or flute-like instrument (called pungi) and a venomous serpent, often a King-Cobra, gets so mesmerized by the rhythm of the tune that it sways its body in dance-like moves until it enters a trance state. At that point of the performance, the snake charmer in a show of speed, agility, and untold bravery taps the King-Cobra at the head with his bare hand and surprisingly lives to do it again! That last part is very important for anyone aspiring to make a career out of it.
There are no amateur snake charmers. These are experienced professionals, trained to handle venomous snakes from a very young age in the family business, which has practiced snake charming for many generations. The snakes have to be dangerous for an audience to pay for the performance. There is no sense trying to hypnotize any garden variety snakes. They are harmless, but no one will pay to see that. Getting paid for the performance is what makes it a profession instead of a hobby.
In a similar fashion, Wall Street is in the business of handling and peddling risky securities. The more novel and more exotic the security, the more excited the investors get. They must buy it, at any price! And Wall Street sure knows how to excite the crowd. It gives them incomprehensible names with confusing descriptions, which makes it impossible to reasonably value them. They organize financial media advertising campaigns to introduce a new company to create a buzz around the name and create buyer frenzy. For instance, they announce a company will go public (sell shares to the public) next month. It can be pre-revenue (has no sales, therefore generates neither earnings nor cashflows) but it develops quantum computing, which will change the world!
Investors wonder “Can anyone explain what that is?” Oh, it is computing using qubits. “Still no clue what that is.” So, all investors really know is that this company has no complete product, makes no money, engages in something they don’t comprehend, which may or may not be useful at all, assuming it ever gets it to work in the first place. But surprisingly, the investor reaction is to disregard all these points and focus on the Wall Street hype that this company will change the world! The typical investor conclusion is “I’ve got to get on this early, sign me up for X thousand shares.” Oh no, you cannot get these many shares. Only a limited number of shares will be sold to the public. “Pleeeeease, I have a big account with you guys, I expect better treatment. Get me the shares.” Ok, just for you, but they may cost you more. “Doesn’t matter, just get them for me.”
Would it make sense for Wall Street to promote safe instruments like Money Market Accounts or Certificates of Deposit? That’s not their business. Safe instruments don’t make as much money as risky ones; thus, safe instruments are left to the banking business. Wall Street is in the business of promoting risky assets at the highest price investors can pay to the issuers. To do this, they need at least two elements:
First, they need to make sure investors cannot calculate the value of the promoted asset. Lack of historical data and vague or confusing descriptions play a key role here. What is the value of a business with no financial information? What is the value of a Bitcoin? More importantly, what is a Bitcoin? People cannot explain it, however, last October people were paying $126,000 for one. But not anymore. This month, they can be had for $64,000. Is this a good price? You cannot answer this question unless you know how to value such a thing. And if you can, then maybe you can tell us what is the proper price for a Melania coin!
The second element Wall Street needs for promoting risky assets is to create and maintain investor excitement about buying securities for future potential high returns. The key here is to distract investors from the price they pay for securities and focus on the premise that markets eventually go higher. This is where Wall Street employs the illusion of using an index as a proxy for the market. Every day the stock market is open, financial news reports on the progress of stock market indices. Wall Street analysts discuss the quarterly and annual stock market index gains as if the index was the market. But it is not!
This is equivalent to the snake used during the snake charmer’s performance. The audience may assume this is probably a random King-Cobra, the performer found hidden in the rocks in the wild a few days ago, and now he will hypnotize it. But that is not the case. The snake used in the show has been handled, fed, and trained by the performer ever since it hatched from the egg years ago. In essence, this is his pet! That’s why the snake doesn’t bite the performer. Out of all the snakes that were raised and trained by the snake charmer, this is the most well-behaved and cooperative one. That’s why it made the show. Even so, proper risk management practices include draining the venom from the snake’s fangs before the show, while keeping it dehydrated to limit its energy and agility. In reality, the exotic deadly serpent of the show is the subdued domesticated pet of the performer. That’s why the whole show is an illusion.
Similarly, the stock market index is the domesticated pet of Wall Street. They want you to think the index is the stock market, but the index is just a mathematical formula. If we refer to the widely used S&P 500 index, this is simply the sum of the market capitalization (stock price multiplied by the number of shares outstanding) of all companies in the index, divided by 503 (oh, another surprise, there’s currently more than 500 stocks in the index). Of course, there are index funds trying to track the index by holding all 503 stocks, but their performance can never match the performance of the index. There is always a tracking error. One of the reasons for this error is that the index is like a self-healing lizard regrowing lost limbs. Every quarter the S&P Dow Jones, who manages the index, throws out the biggest losers and replaces them with up-and-coming companies. Mathematically, replacing 3-4 companies whose market value has dropped a lot, with 3-4 others with much higher market value than those they are replacing, suddenly props up the index. That’s a domesticated pet index managed for reaching higher levels, but it is not the market.
The index funds tracking the index have no choice but to immediately sell the shares of the companies that are getting kicked out of the index and buy those of the companies joining the index. That causes losses for the index funds. They must sell stocks that may have been purchased for $50 per share but now sell for say $5 per share. Since all the index funds try to do this selling at the same time, they may get even a lower price. The index doesn’t book a loss. The index funds do. Furthermore, all the index funds must buy the shares of the incoming 3-4 companies to the index. Doing all the buying at the same time raises their costs. The tracking error grows every quarter.
What’s more, the new entrants are chosen for inclusion into the index simply because their stock prices have been rising, making them expensive acquisitions for the index funds. Paying too much for anything is rarely a recipe for success. For instance, one of the more recent entrants into the S&P 500 index is Carvana (CVNA), a used car dealer. **Exactly one year ago the stock was trading at $148 per share. At the time of inclusion in the index the stock price was $487! **What a bargain to pay three times the price than a year ago! It’s not like the car market, and particularly the used car market, is doing so great that it would justify paying 3x the stock price from 12 months ago. Not surprisingly, following the initial buying spree from the index funds, the Carvana shares have given back a third of the price, currently trading around $330.
Unfortunately, investors fall for the illusion. They see the index moving higher and wonder why their portfolios don’t show similar gains. However, even if all their funds were allocated to an index fund, they still would not match the performance of the index. Keep in mind, the index funds have additional fees and expenses. Furthermore, most investors older than 40 years old should not have all of their funds in an index fund. That’s too risky of an allocation. Typically, the older the investor, the smaller the allocation to stocks should be, thus comparing their portfolios to the performance of the S&P 500 index is not helpful. This would be equivalent to a 70-year-old runner being upset that he cannot match a high school runner’s time at a 100-meter race. Different ages have different risk-taking capabilities, therefore different portfolio allocations and expected returns.
Perhaps something even worse for investors is that since Wall Street focuses heavily on the index, it creates the illusion of safety for stock ownership at any price. If the self-healing index pushes ever higher, then investors conclude “buying even at all-time-high prices must not only be ok but also profitable”. We beg to differ.
Case in point, while the S&P 500 index after the first two months of the year remained within half a percent of the 2025 closing level, stocks of Data Center companies declined -58%, Materials -48%, Fin Tech -50%, Software companies -20% to -60%, Microsoft -30%, Amazon -21%, Intuit -58%, etc. The point here is the index masks the fact that the stock market is actually an exotic venomous snake, and as such it needs to be handled with proper respect and a lot of care. As you can see from the examples above, when stock prices correct, the declines can be fast and substantial, which may induce a certain level of anxiety even to experienced long-term investors.
Wall Street thrives when investors are suffering from FOMO (fear of missing out). That’s when investors become the least careful about the prices they pay for assets. The Wall Street crowd wants to convince you to throw caution to the wind and grab your clarinet, mesmerize that venomous snake, and then you too can tap it on the head and become a hero! Alas, no matter how good your musical skills are, you cannot hypnotize a King-Cobra. Much like all other snakes, it has neither ears nor ear drums. Snakes are deaf and the whole snake charming act is an illusion for naïve tourists. Don’t fall for the Wall Street snake charming illusion.
Acknowledging the fact that the serpent is dangerous is half the battle. Investors can still have the excitement and gains from collecting and trading exotic snakes. Just don’t go tap them on their head as if they were harmless. Better to proceed with caution and grab them by the tail. Better yet, use a long stick to grab them by the tail and do not overstay your welcome. Linger for too long and the serpents can turn around and deliver deadly bites.
**Here are some of the possible ‘bites’ for the immediate future (Bearish Catalysts): **
- The stock market is overextended in both fundamental and technical measures. The market capitalization-to-GDP ratio is at 2.3x and the margin debt-to-market capitalization ratio is at 1.8%- both higher than the values of March 2000, before the DotCom market crash.
- The Private Credit market seems to be reaching the point of reckoning. We have been reporting in our newsletters the problems in firms like Blue Owl, Apollo, and Blackrock. Now, even the Treasury Secretary Scott Bessent said he is concerned. Losses from Private Credit firms could spill over to the banking sector and could possibly cause a 2008-type financial crisis.
- The Japanese Prime Minister Sanae Takaichi won the February 8th national election with a massive 68% super majority. That allows her to proceed with her aggressive stimulus spending plans. Whether she sells Japan’s US Treasury bonds or issues new Japanese bonds to fund this spending, interest rates could be pushed higher, which would be bad for stock prices.
- The US Supreme Court on February 20th found that the tariffs imposed by President Trump under the International Emergency Economic Powers Act (IEEPA, 1977) are not allowed under the Act. The President can block transactions or restrict trade altogether but cannot impose tariffs under IEEPA. The administration is replacing the existing tariffs with new ones under Article 122 of the Trade Act (1974). This, however, adds more complexity to the trade and fiscal pictures. Are the new tariffs capable of generating the same revenue as the previous ones? The tax cuts of 2025 were offset by the anticipated tariff revenue. Without that, the budget deficit may get worse. Also, will the US government be forced to refund the previously collected tariffs? If so, to whom? Typically, uncertainty is not good for stock prices.
- Despite all the AI spending, the 2025-fourth-quarter US GDP (output) came a bit on the light side. It could have been affected by the 43-day government shutdown, where government spending was very limited, or it could be that the figure will be revised higher on the second and third revision it undergoes. What is observed however, is that counties in 3 states (Texas, Kentucky, and New Jersey) are objecting to the construction of data centers (for AI purposes) due to limited electric capacity in their areas. If more counties follow the same path, the AI spending boom and its effect on GDP may be delayed, which would be bad for stock prices.
- Inflation data for December and January came a bit hotter than expected. Both the month-over-month (0.4%) and the year-over-year (2.9%) December Personal Consumption Expenditures (PCE) figures, and the January Producer Price Index (PPI) figures (2.9% yoy and 0.5% mom) came above expectations. Unless the next PCE and PPI figures start coming lower, it would be hard for the Federal Reserve (FED) to initiate more interest rate cuts. A lower cost of money would be better for stock prices.
- The Iran situation seems explosive. The US does not typically move so many military assets in a region just for show. It costs a lot of money to move two carrier groups plus dozens of fighter jets and support planes to the other side of the world. A short-lived conflict that doesn’t affect oil prices for a long period may not be an issue, but a prolonged closing of the Straights of Hormuz would affect both oil and stock prices, just in the opposite direction.
- Let’s not forget the Cuba situation. The country has run out of fuel due to the US embargo and reports from the island point to 19th century living conditions. This cannot last long. Will the Russians or the Chinese come to their aid? If so, will their fleets try to break the US embargo? This one is too close to home for comfort.
- While the release of the Epstein files was not an issue for the stock market, now President Trump has ordered the release of the Alien files to the public. The effect of such a release on the stock market is anyone’s guess. Again, uncertainty is not good for the markets.
On the upside, here are some short-term and medium-term market boosters (Bullish Catalysts):
- The FED is already pumping $60 Billion per month of new liquidity into the system. If you are wondering “where does all this money to keep buying stocks come from?” Wonder no more.
- Tax refunds and bonus depreciation for business capital investments are about to unleash an estimated $2.6 Trillion into the economy. Such spending is typically a GDP and stock market booster.
- Despite our own well-known concerns about the colossal spending for AI (artificial intelligence) projects, the Magnificent 7 firms have committed about $700 Billion collectively in AI spending for 2026. Investors don’t seem to care if this is good or bad allocation of capital. When they hear about more spending, they seem to “buy-buy-buy” more stocks.
- The spending of the top 10% of households (by income) accounts for about half of all the consumer spending. This spending has been resilient despite the bottom deciles of households feeling the pain from high prices. Resilient consumer spending is supportive of stock prices.
- 2026 is a midterm election year in the US, and investors may be expecting the government to do some additional spending, or at the very least to have the “plunge protection team” on standby to bail out the markets if necessary. This creates a type of “stability bubble” where investors may know that stock prices are too high, but may feel the government will not let them decline significantly for fear of losing the elections.
After reviewing the current bullish and bearish market catalysts, we are short-term cautious and medium-term optimistic. This means we believe the stock market needs a decent size correction to flush out excesses and provide a better margin of safety for investors. Despite some price declines within tech and software, the market has not corrected yet. It has just rotated sectors. While the prices of some technology stocks have declined already and are presenting better values than two months ago, investors rotated their money to other sectors, making them ridiculously expensive. Therefore, we would avoid at this point industrials, energy, materials, and consumer staples until they correct to levels resembling fair value. Currently, we are looking more favorably at some of the hardest hit software and technology names, which appear much more enticing right now. This is the essence of contrarian value investing, emphasizing avoiding the herd mentality.
If, however, after reviewing the Wall Street illusion, the current market catalysts, and our opinions above, investors are still overwhelmed with FOMO and feel compelled to invest aggressively at this time, a review of the investor’s risk preference may be in order.
It would be appropriate though to reflect on the famous words of inspector Callahan (Clint Eastwood) in the 1971 film “Dirty Harry” who, while pointing his (potentially empty) Magnum 44 revolver at the bank robber reaching for his own handgun, said: “You’ve got to ask yourself one question” “Do you feel lucky?” “Well, DO YOU…?”
Stay Fierce!